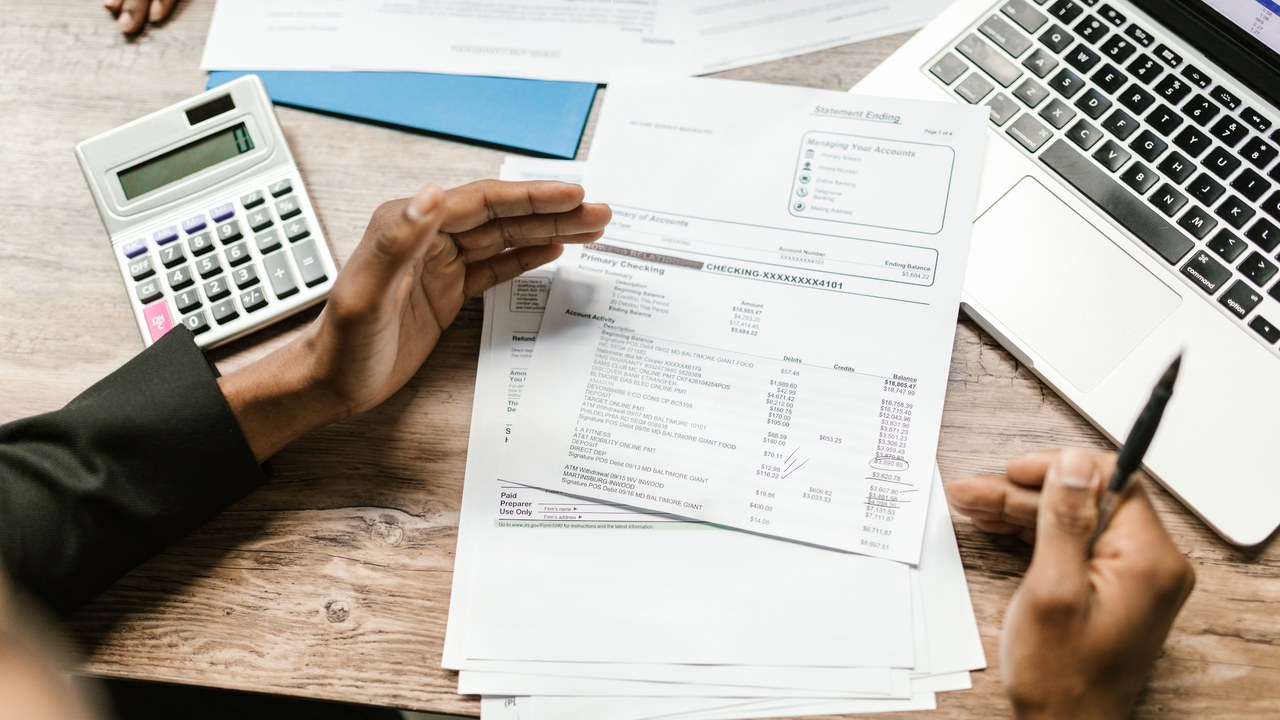
When money leaves a checking account through an electronic transfer the owner did not authorize, the bank does not get unlimited time to sort it out. Federal rules give the institution 10 business days to investigate, and if the dispute runs past that point the bank has to put the money back into the account on a provisional basis while it keeps looking.
The question for anyone whose balance suddenly dropped is when the bank has to restore the money. The Consumer Financial Protection Bureau’s text of Regulation E answers in business days, counted from the day the bank receives the notice of error, and the details decide how long the wait can last.
Retirement deadlines, in your inbox: Miss an enrollment or claim deadline and the money can be gone. Join the Retirement Money Brief and we’ll send you our Bank, Debt & Protected-Benefit Checkup as a welcome gift.
Get the Brief + the bank checkup →
We may earn a commission from links on this page.
Ten business days to decide
Regulation E, shown on the CFPB’s error-resolution page, says a financial institution “shall determine whether an error occurred within 10 business days of receiving a notice of error.” The count is in business days, which leaves out weekends and federal holidays, and it starts when the bank receives the notice.
If the bank finishes inside that period and finds an error, the rule requires it to report the results to the consumer within three business days after the investigation ends and to correct the error within one business day after determining that it occurred.
What happens when the investigation runs longer
A bank that cannot finish in 10 business days has a second option. The regulation says it “may take up to 45 days from receipt of a notice of error to investigate,” but only if it provisionally credits the account “in the amount of the alleged error” within 10 business days of receiving the notice.
That is the rule behind the headline. The provisional credit is the price of the extra time. Consumers keep use of the disputed money while the bank investigates, and the credit can be reversed if the bank concludes that no error occurred.
When 45 days stretches to 90
Some transfers get a longer ceiling. The regulation replaces 45 days with 90 for transfers not initiated within a state, for point-of-sale debit card transactions, and for transfers that occur within 30 days after the first deposit to the account.
New accounts get a second adjustment. For errors involving transfers within 30 days after the first deposit, the 10-business-day periods become 20 business days. A recently opened account therefore waits longer for both the decision and the provisional credit.
The consumer’s own 60-day deadline
The protection depends on timely notice. The regulation says the institution must receive the notice no later than 60 days after it sends the periodic statement showing the error. That is the same 60-day length as the credit card rule on the CFPB’s Regulation Z page, though the two regulations cover different products: debit and electronic transfers here, credit cards there.
Oral reports count, with a condition. The institution may require written confirmation within 10 business days of an oral notice, but it must begin investigating promptly and may not wait for the paper to arrive. Reporting by phone and then confirming in writing, with the date and the name of the person spoken to, keeps both options open.
Provisional credit and the rest of the account
A provisional credit restores spendable money, but it is not the final answer. Before the bank takes back a provisional credit it must give notice, and the regulation says it must honor checks and preauthorized transfers for five business days after that notification.
A separate federal rule protects deposited benefits when a creditor garnishes the account. Treasury’s 31 CFR 212.2 governs how banks handle Social Security, SSI and other federal benefit deposits at that moment, and it addresses a different problem from an unauthorized transfer. A transfer dispute turns on the notice date, the statement date and the business-day count.
With money gone from the account, which day is the bank’s 10-business-day mark?
An unauthorized transfer that sits unreported past the 60-day notice window can leave the account owner without the regulation’s protections, and a dispute with no notice date gives nobody a day to count business days from. For someone living on a benefit deposit, a few days without the money is a real cost.
The Bank Account & Debt Protection Kit covers the 2-month bank protection rule and the frozen-account response, so a benefit recipient knows what the bank must shield and what to send when an account freezes. Part 2, Money They Cannot Touch, and Part 3, Keeping Benefits Provably Exempt, lay out how to keep deposited benefits identifiable.
This article was produced with AI assistance and edited for accuracy against the sources linked above.