
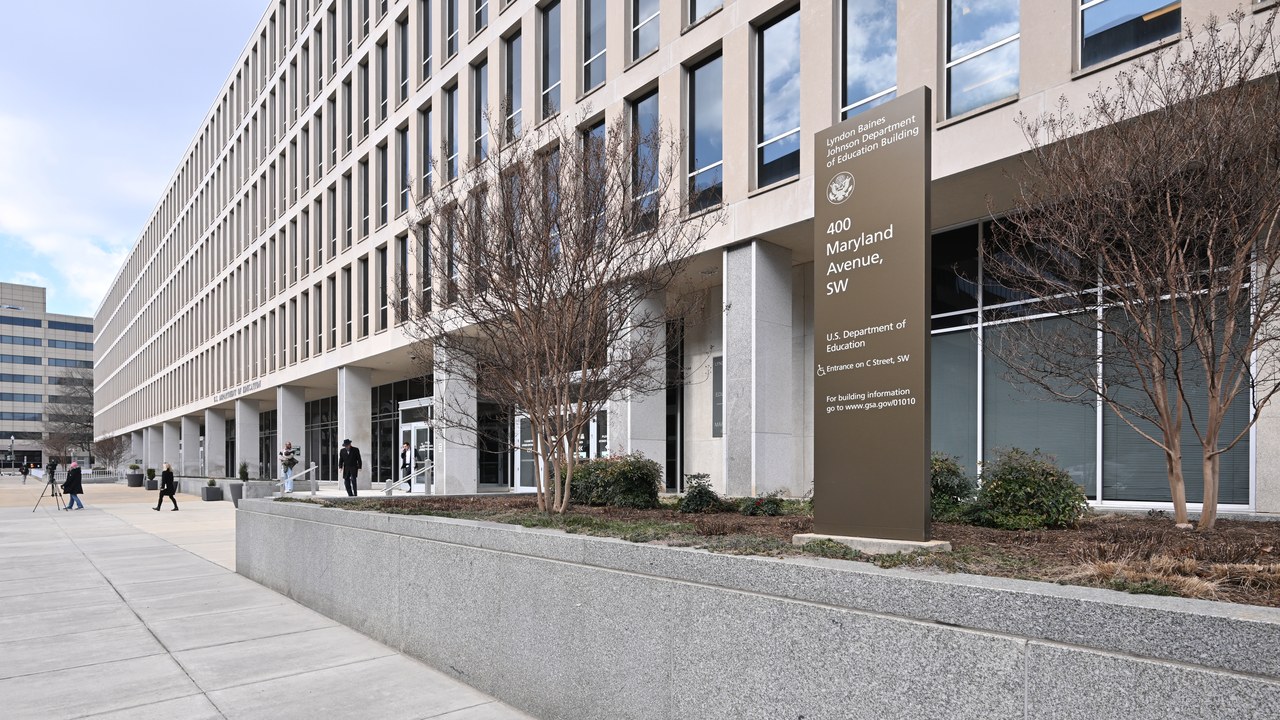
Treasury says approved applications for student loan rehabilitation are up 69 percent since it joined the Education Department on defaulted loans less than six months ago. The two agencies announced the figure on Sept. 30 as they opened the Defaulted Loans Support Center, an online portal at StudentAid.gov for borrowers whose federal loans are in default. Treasury’s announcement does not say how many approvals the 69 percent represents or what they were measured against.
What the agencies reported
The release says the Treasury-Education partnership “delivered a 69 percent increase in approved applications for loan rehabilitation” in fewer than six months since its official launch. It adds that consolidations out of default have risen 95 percent after a technical issue from the previous administration was corrected, again with no baseline given. A third figure comes from early users of the new portal: Treasury says 89 percent found the application easy to complete, 86 percent understood what to do next and 84 percent said the process took a reasonable amount of time.
The scale of the problem is the other half of the release. More than 5 million borrowers have been in default for over six years, and another 5 million defaulted within the past year. Treasury Secretary Scott Bessent framed the work as “restoring fiscal responsibility to our nation’s $1.7 trillion federal student loan portfolio.” Education Secretary Linda McMahon said the department “was never intended to serve as the fifth largest bank in America.”
For a borrower in default, the percentages matter less than the paths. The portal lets borrowers apply online to rehabilitate or consolidate a defaulted loan, make payments and review discharge options, Benzinga reported. The decision a borrower faces is which route out of default to take and how soon to start.
The temporary 1 percent rate cut for borrowers who consolidate and enroll in autopay now runs on an extended Dec. 31, 2026 enrollment deadline, so the first date to watch in this story is the end of the year.
Get the next update the morning it lands →
Rehabilitation, step by step
Federal Student Aid’s rehabilitation guide says a Direct Loan or FFEL Program loan is rehabilitated through nine on-time, voluntary payments within 10 consecutive months, and one missed payment in that stretch is allowed. The standard payment is 15 percent of annual discretionary income divided by 12. A borrower who cannot afford that can submit the Loan Rehabilitation Income and Expense form to ask for an alternative amount, which may be lower.
The guide says rehabilitation removes the default status and stops collections. Wage garnishment and Treasury offset may continue until the loan is out of default or the borrower has made at least five rehabilitation payments. Once out of default, borrowers can again receive federal student aid, including grants, work-study and loans.
Why default gets expensive
Federal Student Aid’s default guide says a loan goes into default after about 270 days without scheduled payments. After more than 360 days unresolved, the government can start involuntary collections. Wage garnishment can take up to 15 percent of a paycheck, and Treasury offset can withhold a federal tax refund and certain federal benefits such as Social Security, with a written notice by mail before it starts.
The same guide lists the ways out: paying in full, rehabilitation, consolidation, or a repayment agreement. Consolidation is faster than rehabilitation, but unpaid interest and collection costs are added to the balance and the default record stays on the credit history. Rehabilitation takes several months and removes the default record from the credit history.
Starting with the Default Resolution Group
The free official route is the new portal at StudentAid.gov/default-support, or the Department of Education’s Default Resolution Group at 1-800-621-3115. The group’s online account runs through MyEdDebt.ed.gov, which requires a separate account built with a Social Security number, since a StudentAid.gov login does not work there. Borrowers with FFEL Program loans contact the guaranty agency they were assigned.
Before starting, a borrower should gather the loan types, the servicer or guaranty agency name, last year’s income and monthly expenses, and any garnishment or offset notice with its dates. The notice dates matter: Federal Student Aid says a first payment within 30 days of a wage garnishment notice, or within 65 days for a Treasury offset notice, can help avoid those collections.
The default guide also carries a warning. The Default Resolution Group does not charge for its services, so anyone asking for an “enrollment,” “subscription” or “maintenance” fee to get a borrower out of default is not the government.
More Financial Reading
- 18 Ways Out of 22% Credit Card Interest
- 24 Ways to Stretch a $2,087 Social Security Check
- 17 Ways Retirees Are Tapping a Record $14.9 Trillion in Home Equity
This article was produced with AI assistance and edited for accuracy against the sources linked above.


