
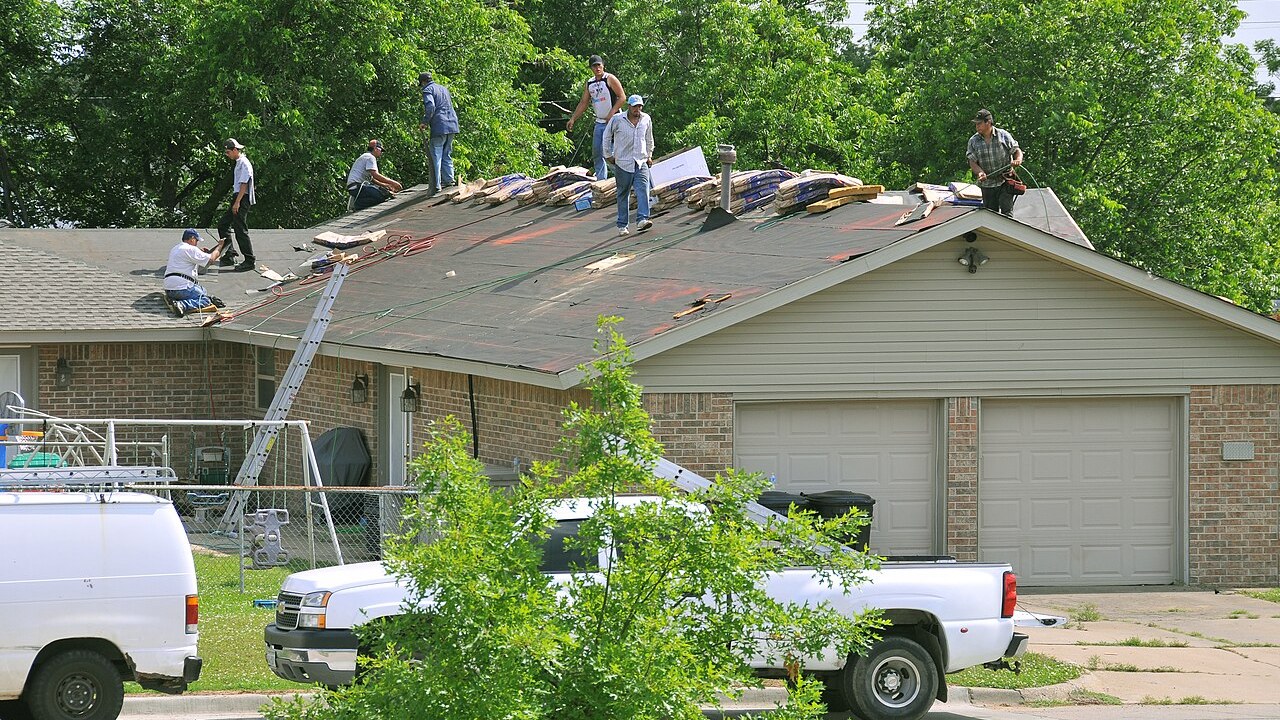
Homeowners in Minnesota and Colorado opened last year’s renewal notices to some of the steepest home insurance increases in the country, as insurers priced in years of hail, wind and wildfire losses. Minnesota’s average annual premium rose from $2,632 to $3,530 over 2025, and Colorado’s climbed from $3,032 to $3,996, according to an industry report that tracked rates across all 50 states. For a retiree living on a fixed income, or a family working around a tight monthly budget, an increase of that size can land like an unplanned mortgage payment, even though nothing about the house itself has changed.
Minnesota’s two-year climb reached 64 percent
Minnesota logged the largest single-year increase of any state in 2025, with its average annual policy rising 34 percent to $3,530, according to Insurify’s 2026 Insuring the American Homeowner report. Stacked on a 22 percent increase the year before, the state’s premiums are now up 64 percent, or $1,373, since 2023 — the steepest two-year climb Insurify tracked anywhere in the country, and enough to push Minnesota from the 21st most expensive state for home insurance to the ninth. The run-up traces back to insurers losing money on Minnesota homeowner policies in 2022, when claims cost $158 for every $100 collected in premiums during the state’s costliest year on record for storm damage, followed by a hailstorm that caused roughly $1 billion in damage across the Twin Cities in 2023. Insurers had a calmer year in 2024, which is part of why Insurify projects a far smaller 4 percent rise, to $3,654, in 2026.
Free relief finder: Property-tax freezes, exemptions and utility help for older homeowners usually only apply after someone asks. See what to look for with the free relief finder.
Free download from RetireShield. Getting it also signs you up for the free Retirement Money Brief, a weekday email. Unsubscribe anytime.
Colorado’s hail and wildfire losses keep compounding
Colorado wasn’t far behind, with premiums up 33 percent in 2025 to an average of $3,996, and up 55 percent, or $1,412, since 2023, according to Insurify’s 2026 Insuring the American Homeowner report. Hail-producing convective storms are the single biggest driver of the state’s rates, accounting for anywhere from 26 percent to 54 percent of a Colorado homeowner’s premium depending on the county, while wildfire risk adds another 1 percent to 25 percent on top of that. Four of the state’s five largest wildfires on record have burned since 2020, and insurers are still pricing that exposure into new policies even as Insurify projects a milder 4 percent increase, to $4,164, for 2026. The typical Colorado policy now covers a home valued near $324,724, so even a moderate percentage increase translates into a meaningful jump in a household’s monthly escrow payment.
Iowa, Nebraska, Oklahoma and South Carolina show the same pattern
The jumps weren’t confined to two states. Iowa’s average premium rose 28 percent to $2,802 in 2025, Nebraska’s rose 25 percent to $4,028, Oklahoma’s rose 24 percent to $4,962, and South Carolina’s rose 20 percent — the full list of states where rates climbed at least a fifth in a single year. Of those six, only Iowa still sits below the national average, though its cost has risen 54 percent over the past two years, the third-largest two-year jump behind Minnesota and Colorado. Illinois, Louisiana and Michigan also landed on the list of states where costs have jumped more than 35 percent since 2023, with Illinois alone up 48 percent, or $1,088, over that span. Insurify ties the broader pattern to severe convective storms — the hail, wind and tornado events concentrated in the Midwest and Great Plains — which caused more than $52 billion in insured losses across the country in 2025, the third-highest total on record behind only 2023 and 2024.
The national bill is still outrunning inflation
Nationally, the average home insurance policy rose 12 percent in 2025 to $2,948, and Insurify projects another 4 percent increase, to $3,057, by the end of 2026 — the fifth straight year of increases and roughly $900 more than the average homeowner paid in 2021. The gap between expensive and cheap states is also widening: premiums rose about three times faster last year in the 25 most expensive states, at 14 percent, than in the 25 cheapest, at 5 percent. Florida remains the single most expensive state at $8,292 a year after an 18 percent jump in 2025, while only five states saw rates fall or hold flat, led by North Carolina’s 6 percent decline. Insurify’s state-by-state breakdown shows California is projected to rise fastest of any state in 2026, at 16 percent, as insurers work to recover wildfire losses within the state’s regulatory limits. Faced with bills like these, roughly one in four homeowners surveyed by Insurify said they would drop coverage entirely if they could — a move the firm calculated would save the average household $281 a month, but one that would leave a mortgaged home, and the equity in it, unprotected against the same storms driving the increases in the first place. Nearly half of the homeowners Insurify surveyed said home insurance should be optional rather than lender-required, and many are already responding to the cost by raising their deductibles, trimming coverage limits or shopping for a new policy at renewal instead of automatically accepting an insurer’s proposed increase.
Property tax is the other big bill that moves on its own schedule
Insurance premiums are not the only housing cost that climbs without warning for a homeowner who already paid off the mortgage. Property tax bills, along with the freezes and exemptions attached to them, run on a separate calendar that many longtime owners have never checked, and the same is true of the assistance programs built for heating, cooling and basic home repairs.
The Senior Property Tax & Home-Cost Relief Kit is an 11-page kit covering the 5 kinds of property-tax relief, the circuit-breaker credit that includes renters, and heating, cooling and home-repair help, along with an application log and renewal calendar to track deadlines.
See The Senior Property Tax & Home-Cost Relief Kit.
AI-assisted research and drafting; reviewed by an editor.


