
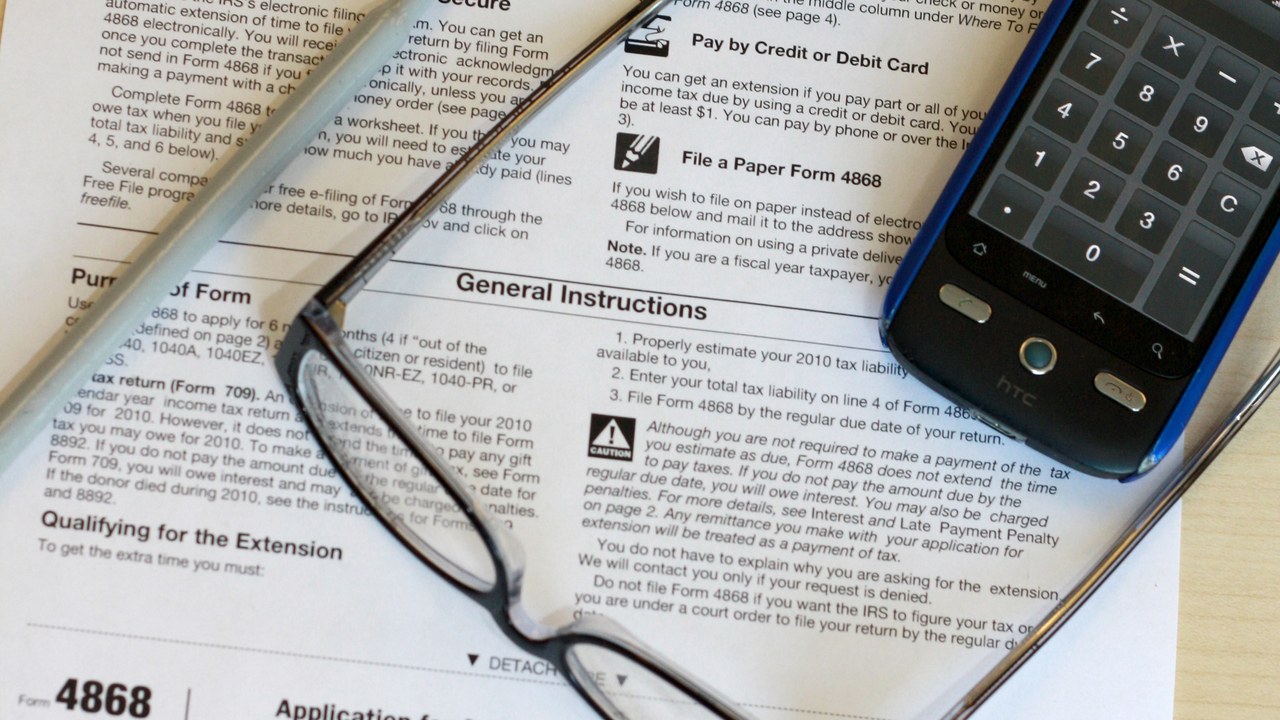
A common mix-up trips up filers every extension season: requesting more time to file a 2025 tax return did not buy more time to pay what was owed on it. Form 4868 pushed the paperwork deadline out to October 15, 2026, but the amount owed still came due back on April 15, and the IRS has been running penalty and interest charges on any unpaid balance since that date. For a household that filed the extension form and assumed the clock reset on everything, the six-month cushion on paperwork can mask a cost that has been accumulating in the background the entire time.
What the Extension Paperwork Actually Moves
The IRS lists three ways to request the automatic extension: pay what is owed online and check a box marking the payment as an extension request, file electronically through IRS Free File, or mail Form 4868, the Application for Automatic Extension of Time To File. Every version does the same narrow thing. The agency’s own extension instructions state that the request extends the filing deadline to October 15 without a late-filing penalty, and that any tax owed must still be paid by the original April filing date, since the extension applies only to the return itself.
Requesting the extension still requires estimating the amount owed for the year and subtracting whatever has already been paid through withholding or estimated payments; the form asks for that number even though filing it only buys extra time to finish the actual return, not extra time to settle the balance it describes.
The same boundary holds even for the extensions built around travel or service. Topic no. 304 on filing extensions explains that U.S. citizens and resident aliens living outside the country, or on military duty abroad on the due date, receive an automatic two-month extension to roughly June 15 without filing anything, and can add the standard six-month extension on top of that. Even then, the guidance is direct: an extension of time to file “is not an extension of time to pay,” and interest continues to accrue on any balance not paid by the original, unextended due date.
Free download: What each refund-status message means, the direct-deposit and paper-check paths, and when to follow up with the IRS. Get the free refund delay decision tree.
Free download from RetireShield. Getting it also signs you up for the free Retirement Money Brief, a weekday email. Unsubscribe anytime.
The Balance That Stayed Due on April 15
Whatever a household owed for the 2025 tax year was fixed at the original April due date regardless of when the return itself gets filed. Topic no. 653 on IRS notices, penalties and interest explains that interest on an unpaid balance begins accruing from that unextended due date and compounds daily, calculated quarterly at the federal short-term rate plus three percentage points. That interest keeps running whether the return is filed in April, in July, or on the extended October deadline; the extension changes when the paperwork is due, not when the interest clock starts. The same guidance notes that the IRS applies any payment first to the tax owed, then to penalties, and only then to interest, so a partial payment reduces what future penalty and interest charges are calculated against before it reaches the interest balance itself. The exact rate for the current quarter is a separate, regularly updated figure the agency publishes on its own.
The Half of One Percent That Keeps Adding Up
Filing on time under an extension does not eliminate the second penalty most people don’t think about until a notice arrives. The same IRS overview describes a failure-to-pay penalty of one-half of one percent of the unpaid tax for each month, or part of a month, that the balance goes unpaid, up to a maximum of 25 percent of the amount owed. That rate rises to one percent a month if the balance is still unpaid ten days after the IRS issues a notice of intent to levy property, and it drops to one-quarter of one percent for any month covered by an approved installment agreement.
For a household that filed Form 4868 in April and finished the actual return in September, the extension protected them from the steeper failure-to-file penalty, the one that can run five percent a month, but it never touched this smaller, slower charge. Six months at the half-percent rate adds up to three percent of the unpaid balance on top of accruing interest; on a hypothetical $5,000 balance carried the full six months, the failure-to-pay penalty alone would add roughly $150, separate from whatever interest accrued over the same stretch. That is the part an extension never covered.
A Narrow Path to Reduce a First Penalty
Households facing either penalty for the first time have one formal option before appealing to individual circumstances: First Time Abate relief, described in the same IRS guidance, which can waive certain penalties for taxpayers with a clean compliance history over the prior three years. Short of that, the agency says it may reduce filing and payment penalties when a filer shows reasonable cause and demonstrates the failure wasn’t due to willful neglect, with a good-faith payment toward the balance often cited as evidence of that intent. Interest, by contrast, is not something the IRS generally reduces; it continues to accrue until the underlying tax, penalty and interest are paid in full.
Reading the Penalty and Interest Notice That Follows
A household that pays down a penalty and interest balance months after the April due date typically gets a follow-up notice listing dollar totals without spelling out which charge covers which month. The extension paperwork and penalty rules described above explain how the charges accumulate, but not how to read the letter that eventually itemizes them or trace a refund if an amended return later turns up an overpayment.
The IRS Refund Recovery Kit is built around a notice decoder and the refund-trace steps for Form 3911, aimed at exactly that kind of after-the-fact paperwork.
See the notice decoder and the refund-trace steps in The IRS Refund Recovery Kit.
AI-assisted research and drafting; reviewed by an editor.


