
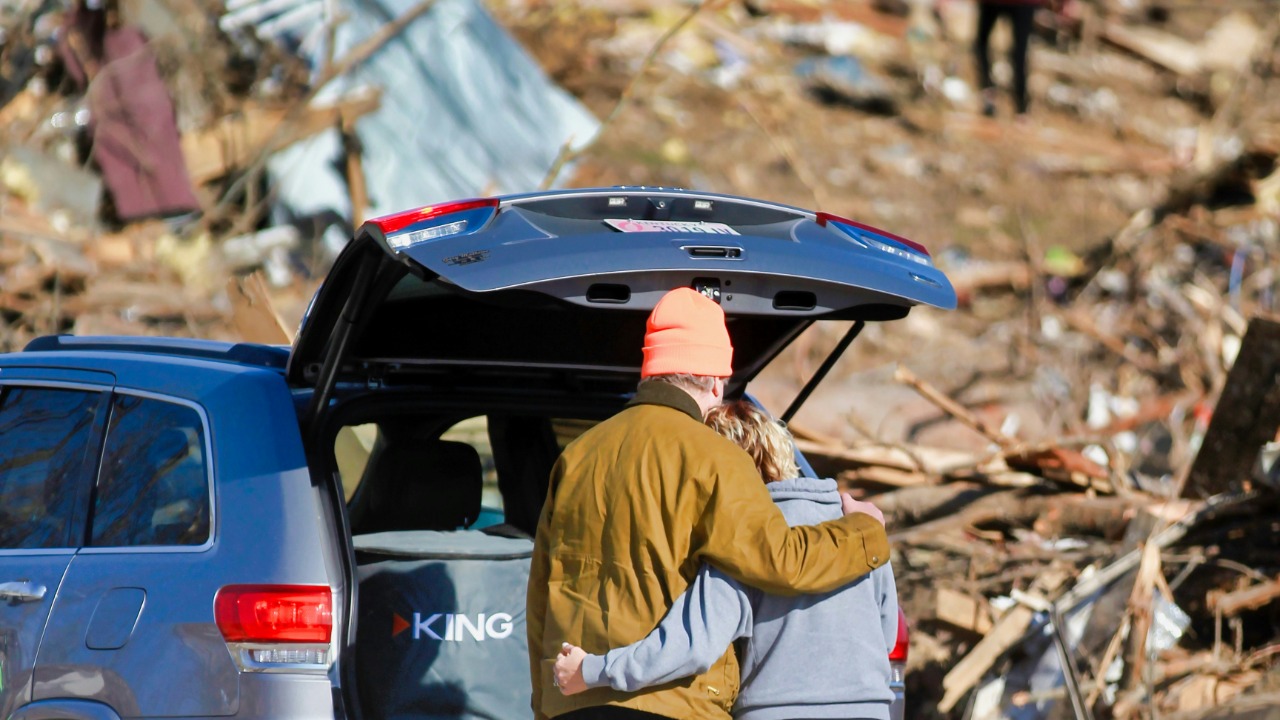
A flood, wildfire or tornado can destroy the receipts needed to document the property it destroyed. The IRS says a missing paper trail does not end the process: bank and card statements, photographs, videos, contractor records and county files can rebuild it. The same evidence may matter for a tax return, federal assistance application or insurance reimbursement.
Start with records held somewhere else
Banks and credit-card companies often preserve statements long after a household copy is gone. Those records can identify the merchant, date and amount of a purchase, creating a starting point for property lists and replacement-cost research.
The IRS reconstruction guide published September 2 also points taxpayers toward online tax accounts, mailed transcripts and Form 4506-T. A tax return transcript is commonly needed after a disaster because it recreates filed income information without requiring the original return.
Free retirement updates: Miss an enrollment or claim deadline and it may be gone. Our free Retirement Shield newsletter keeps readers ahead of the ones that matter. Get the free newsletter.
Photos establish condition as well as ownership
Old family photographs and videos can show furniture, electronics, appliances and improvements that were present before the loss. Images taken after the event can document the extent of damage. Together they can establish both that an item existed and how its condition changed.
The IRS’s current Publication 547 on casualties and disasters says photographs taken after a casualty can help establish the condition and value of damaged property. Images after repair or replacement may also help. Appraisals can support the change in fair market value, although their cost is not itself part of the casualty loss.
Online listings can help estimate fair market value for personal property when an original invoice is unavailable. The useful comparison is a similar used item in comparable condition, not automatically the cost of a brand-new premium replacement. A dated photo can narrow the age and model, improving that comparison.
Homes and vehicles have institutional records
A title company, escrow agent or lender may retain purchase documents for a home. Contractors can provide statements showing when improvements were made and what they cost. Friends or relatives who saw the property before and after the damage may provide written descriptions.
County assessor files can supply older property records when private files are gone. Vehicle dealers may have the original purchase contract, and libraries or valuation services can help identify a vehicle’s current fair-market value. These records build different parts of the same financial picture: basis, pre-loss condition and post-loss value.
The evidence should be organized by item or project rather than delivered as an unsorted stack. A simple inventory can pair each damaged asset with its purchase evidence, photographs, estimated pre-loss value, insurance treatment and replacement or repair documentation.
Insurance reimbursements change the tax calculation
Proof of a gross loss is not the same as proof of a deductible loss. Publication 547 says insurance and other reimbursements generally must be subtracted when calculating a casualty loss. If reimbursement is reasonably expected, the tax loss may not be treated as sustained until the outcome is known with reasonable certainty.
Tax treatment also depends on whether the casualty qualifies under current law. Personal-use losses have specific disaster and deduction rules, and state relief, insurance payments and grants can interact differently. The IRS’s Publication 547 hub points to the current edition and related forms rather than relying on an older disaster-year worksheet.
That is why reconstruction should serve several files at once but not assume every agency values the evidence identically. An insurer may apply policy replacement-cost terms, a federal aid program may use its own documentation standard, and the tax return follows federal casualty-loss rules.
The practical conclusion from the September 2 IRS guidance is reassuring and bounded: receipts are useful, but they are not the only proof. Statements, photos, videos, contractor records, title files and assessor data can collectively reconstruct a defensible disaster-loss record when the originals disappeared with the property.
A reconstruction file works best when every estimate points to its source. A spreadsheet can list the lost item, approximate purchase date, original cost, evidence available and replacement-cost reference. The file should preserve uncertainty instead of turning a rough memory into a precise unsupported number.
Different relief systems may value the same property differently. Insurance replacement cost, tax basis, fair market value and federal assistance are not interchangeable. Records can support several applications, but each calculation must follow the rules of the program receiving it.
Inside the kit
The 2-month bank protection rule, the debt-validation steps, the frozen-account response and a protected-funds and dispute log.
The Bank Account & Debt Protection Kit includes a 10-page kit, the 2-month bank protection rule and the debt-validation steps.
Open The Bank Account & Debt Protection Kit.
This article was produced with AI assistance and reviewed by a human editor. Figures are linked to their primary sources; where a claim could not be verified from the public record, we say so.


