
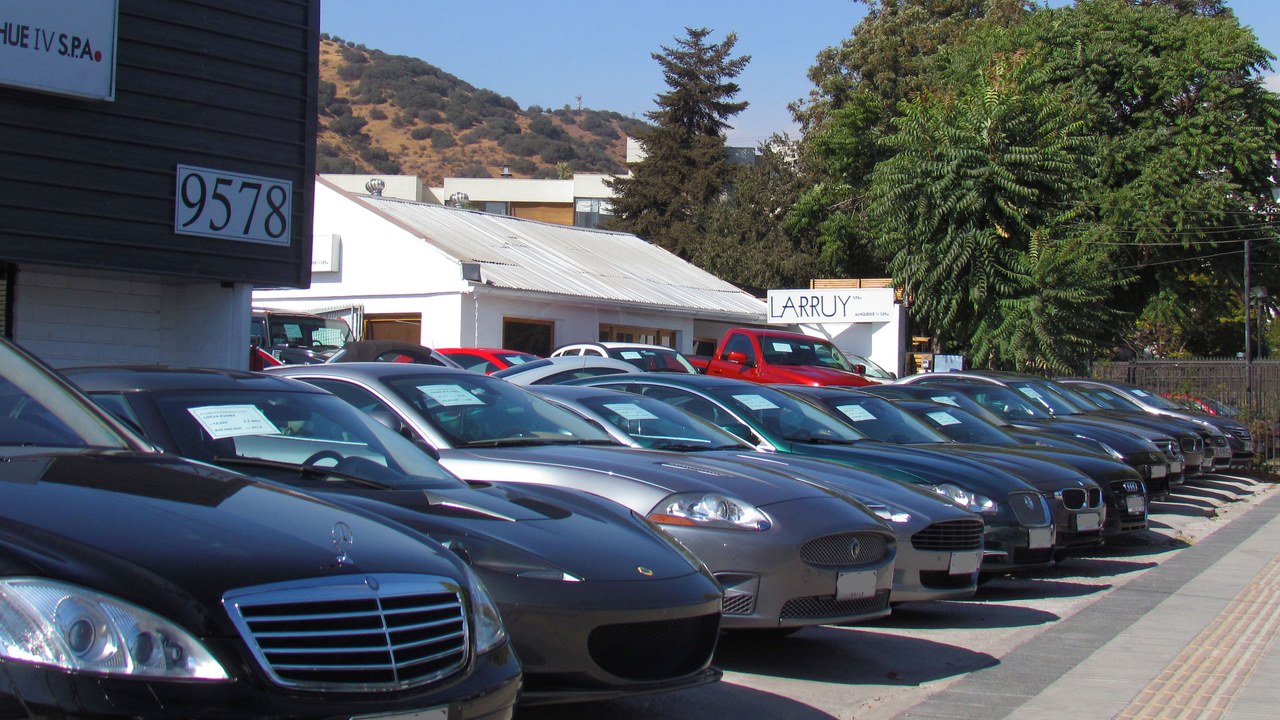
Federal regulators moved this month to spell out, in plain terms, what an advertised car price is supposed to mean. On September 15, 2026, staff at the Federal Trade Commission published a set of frequently asked questions telling the auto industry exactly which costs belong in the sticker price and which ones a dealer can leave out. The guidance does not create a new law; it explains how a decades-old ban on deceptive advertising applies to the modern car lot, from dealership websites to roadside banners. For a household pricing a vehicle this fall, the practical effect is a clearer definition of what the number in the ad is actually supposed to include before anyone signs anything.
The “Walk-In-And-Pay” Standard Behind the Guidance
That standard rests on Section 5 of the FTC Act, the law barring unfair or deceptive practices, which the Commission’s staff says has applied to advertising for decades. Section 5 enforcement long predates this specific guidance, and FTC staff has used it against sellers of goods ranging from mattresses to timeshares. Auto retailing gets its own explainer because price shows up across so many separate touchpoints, from dealership websites and text messages to roadside banners and in-person negotiation, and a mismatch at any one of those touchpoints can mislead a shopper before a car is ever seen in person.
The core rule, according to the FTC’s Automobile Industry Pricing Transparency FAQs published September 15, 2026, is that the advertised price must be the actual price that any consumer can walk in and pay to purchase the vehicle, excluding only charges a federal, state or local government requires the consumer to pay directly. Dealer-required charges that a government merely authorizes, such as many document fees, still have to be built into that number.
Free download: The first-hour steps in order, who to call at banks, agencies and credit bureaus, and what to document. Get the free scam and identity-theft action card.
How Document Fees, Rebates and Financing Discounts Get Folded In
The FAQs walk through concrete dollar examples. If a dealer advertises a vehicle at $40,000 and would also charge every buyer an $85 document fee, the advertised number has to read $40,085, with no further charges layered on beyond anything the government itself requires. The document explaining these examples, published alongside the press release, also addresses what happens when a dealer quotes a lower fee to some shoppers and a higher one to others: the ad has to reflect the higher, fully mandatory figure, not the discounted one a handful of buyers might receive.
The same logic applies to manufacturer suggested retail prices, rebates and financing discounts. A dealer can still advertise a $34,999 vehicle alongside a $1,000 discount for a specific group, or list the manufacturer’s suggested price next to a lower one, as long as the price every shopper can actually pay is the most prominent figure in the ad and the terms of any narrower discount are clearly stated. Burying the real price in smaller type, or placing a rebate-adjusted number where it draws more attention than the price everyone qualifies for, does not satisfy that standard. Leasing ads face the same discipline: any processing fee due upfront in a lease has to be included in whatever figure the ad presents as the amount due at signing, and none of this changes a dealer’s separate obligations under the Consumer Leasing Act, Regulation M, the Truth in Lending Act or Regulation Z.
The March Warning Letters to 97 Dealer Groups
The FAQs did not arrive out of nowhere. In March 2026, the Commission sent letters to 97 auto dealership groups nationwide, warning them that the price advertised has to be the actual, all-in price, including mandatory fees, that a buyer will be required to pay. That earlier action, described in the Commission’s own warning-letter announcement, set up the more detailed FAQs released six months later, and the September release explicitly points back to it as the reason dealers needed clearer answers about which specific costs are covered. The dealership groups singled out were not named publicly, and the March letters functioned as a compliance nudge rather than a formal enforcement action, but they signaled where FTC attention was already concentrated months before the FAQs arrived.
Guidance, Not a New Regulation: Why the Distinction Matters
It matters that this document is staff guidance rather than a formal regulation. The FAQs themselves note that price transparency is not a new requirement and that the FTC Act’s Section 5 protections have applied for decades; nothing about them is proposed, pending in a rulemaking docket, or facing a court challenge. FTC staff describe the FAQs as accurate statements of existing law rather than binding rules, which means the underlying obligation on dealers was already in force before September 15 and remains in force now, with the FAQs simply making the agency’s expectations explicit and easier to point to. Bureau of Consumer Protection Director Christopher Mufarrige framed the release as part of a broader Commission priority on price transparency, not a standalone action, when the agency announced the FAQs on September 15.
What This Changes for Someone Pricing a Car This Fall
For a household comparing listings this season, the practical value of the guidance is a specific phrase to hold a dealer to: the number in the ad should be the number that shows up on the paperwork, aside from taxes and other charges a government office actually requires. The FTC has also renewed its invitation for the public, including dealers who feel undercut by competitors’ pricing, to file a report at ReportFraud.ftc.gov with copies of the ad and the contract when the two numbers do not match. That single mechanism, more than any press release, is how the agency says it will keep testing whether the September guidance changes behavior on the lot.
The First Hour That Decides How a Bad Deal Turns Into Fraud Recovery
Pricing rules like the FTC’s guidance cover what a dealer has to put on the sticker, but they do not cover what happens if a deceptive sale turns into something worse: a card number copied off paperwork, a financing application filled out with stolen details, or a signature rushed through before anyone had time to read it. Few households have a plan ready for that moment, and the window that matters most for limiting the damage is the first sixty minutes after someone realizes something is wrong.
The Senior Fraud Defense & First-Hour Recovery Kit lays out the family code word for verifying a call or visit is legitimate and the free credit-freeze steps for locking down accounts before further damage is done.
Read the family code word inside The Senior Fraud Defense & First-Hour Recovery Kit.
AI-assisted research and drafting; reviewed by an editor.


